Skip to content

TvF Consulting, Warsaw, all of Poland

Every number has a source
the other side can verify

Business valuation, financial analysis and AI-assisted management reporting

I value businesses, break profitability down to its drivers and build tools that read financial statements automatically. I work from source data – statements filed with the commercial register, ledgers, time records – not from materials prepared by the seller. For owners, boards and investors – in Warsaw and across Poland.

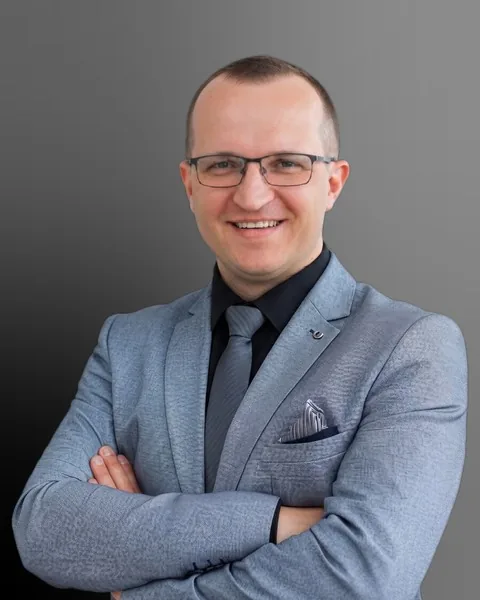
Tomasz Fordymacki – portrait

Tomasz Fordymacki

Financial adviser, valuation, transaction analytics, management reporting

  • A model, not a slide deck – you get a file that calculates
  • Three valuation methods reconciled into one number
  • Confidentiality from the first phone call

8

financial analyses

one engine, over a dozen companies compared, the same method

7

valuation models

income, market and asset approach in each

11

applications and tools

built from scratch, some of them public

335

scripts

they do the repetitive work so I can do the rest

How I work

Four steps, always the same

The order is not accidental. The most expensive mistakes come from skipping the first step.

  1. 01

    Source data

    Register filings in machine-readable form, a ledger export, time records, contracts. Not summaries prepared to support a thesis. If data is missing, I say so at the start rather than in the conclusions.

  2. 02

    Normalisation

    One-off events, related-party transactions, owner’s remuneration, costs unrelated to the business. Every adjustment has a number, an amount and a justification – so each one can be argued separately.

  3. 03

    The model

    The numbers are calculated in the file, not in my head. Changing an assumption recalculates the whole model, and closing checks make sure the balance sheet ties and the cash flow reconciles to zero.

  4. 04

    The document

    At the end there is something you can put on the table: a workbook, a report and a presentation stating the same number. Three documents that contradict each other are worse than none.

AI and automation

Machines do the counting, a person answers for it

I use language models and my own scripts where the work consists of reading documents and retyping numbers. Decisions on adjustments, weights and the conclusion stay with me – and are documented so they can be checked.

Reads

Registry filings in XML, ledger exports, time records – loaded and reconciled automatically, a dozen companies with one method.

Checks

Around a hundred ledger-control rules and several hundred tests that catch errors before they reach the report. A document that checks itself.

Reports

Dashboard, report and presentation generated from one model, in Polish and French – the same number everywhere, no retyping.

What I never hand to the model

Normalisation adjustments, valuation method weights, forecast assumptions and the final conclusion. The model speeds up reading and computing; responsibility for the number on the table is mine.

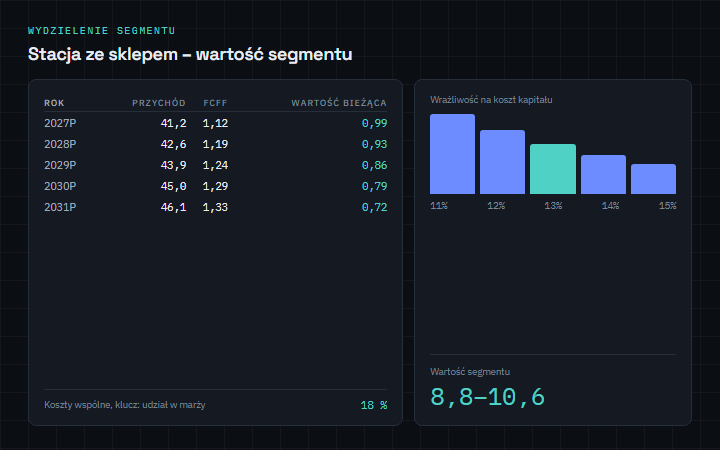
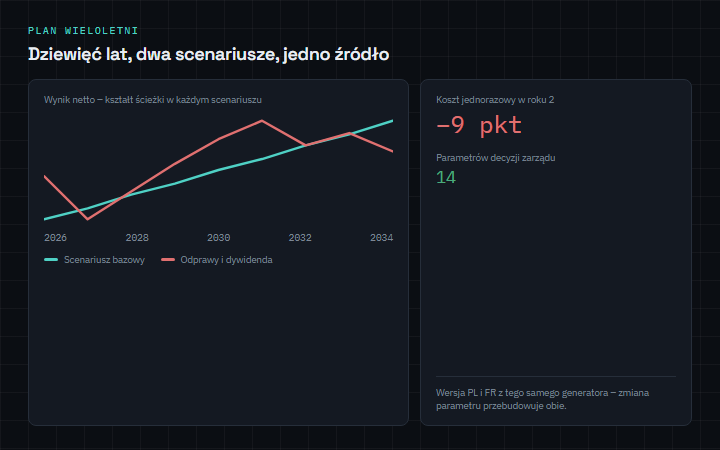
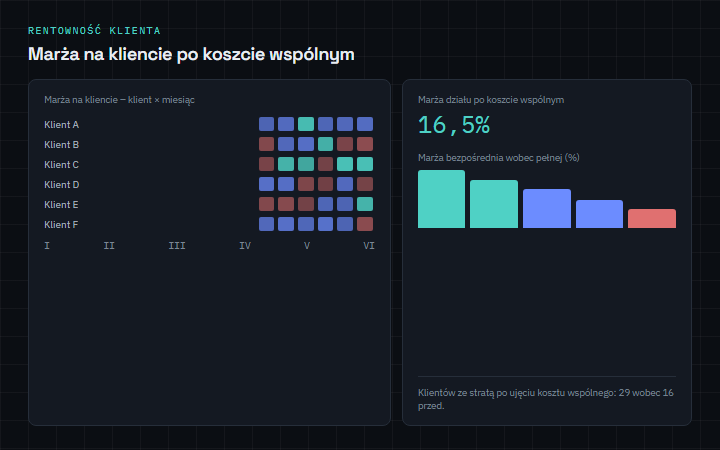
What automation looks like in practice

Glossary

Speaking the same language

Half the misunderstandings at the table come from two sides reading the same word differently. These are ten terms that come up in every conversation about value – with a definition and with the mistake most often made around them.

10 terms
  • Common mistake

    Comparing one company’s enterprise value with another’s share price. These are two different numbers and they differ by net debt.

  • Common mistake

    Treating EBITDA as cash flow. It ignores working capital, capital expenditure and tax – a company with positive EBITDA can still fail.

  • Common mistake

    Treating the whole cash balance as surplus. Part of it is working capital the business needs to operate and cannot be taken out.

  • Common mistake

    Ignoring it while growing. Rising sales always consume cash through working capital – the main reason growing companies fail.

  • Common mistake

    Taking the weights from the current book balance sheet rather than from target values. The valuation then depends on an accidental year-end position.

  • Common mistake

    Underestimating its weight. It is usually 60–80% of the whole valuation, so a small change in the growth assumption moves the result more than the entire forecast.

  • Common mistake

    An adjustment without evidence. The seller always normalises upwards and the buyer downwards – a document settles it, not a statement.

  • Common mistake

    Reaching for listed-company multiples for a small private business. Indicative ranges for Polish SMEs in 2025–2026 are 3–6× for small and 5–8× for mid-sized companies – depending on sector, growth and data quality.

  • Common mistake

    Skipping the test. Healthy companies keep conversion above 70–80%; a persistently lower figure means the profit is sitting in receivables.

  • Common mistake

    Reading the ratio without context. In Polish banking practice (2025–2026) comfortable lending reaches about 3.0×; above 4.0× the conversation is about restructuring, not growth.

From LinkedIn

What I have been posting

Short posts about company numbers – each leads to a calculator or article that develops the topic.

  • Cztery geometryczne dźwignie na granatowym tle z siatką

    9 October 2026, Post in Polish

    Podwyżka cen o 3 % może dać więcej niż rok walki o nowych klientów.

    W firmie z marżą EBITDA 9 % podnosi wynik o około jedną czwartą – nawet gdy zakładam, że 30 % efektu ucieknie razem z częścią wolumenu. Cięcie kosztów stałych o 5 % daje zwykle drugie tyle. Skrócenie spływu należności o…
  • Dwa geometryczne elementy układanki zbliżające się do siebie; tylko część krawędzi pasuje i świeci turkusem

    8 October 2026, Post in Polish

    Siedem liczb, zanim zapłacisz za due diligence.

    Przejęcie ma sens, gdy trzy rzeczy są prawdziwe naraz: cel pasuje do Twoich klientów i produktów, synergie da się wskazać na konkretnych pozycjach kosztów, nie „około 10 %”, dług grupy po transakcji zostaje poniżej…

  • Grafika do posta na LinkedIn: Każda liczba w wycenie powinna mieć źródło, które druga strona może sprawdzić. Także ta pierwsza, orientacyjna.

    7 October 2026, Post in Polish

    Każda liczba w wycenie powinna mieć źródło, które druga strona może sprawdzić. Także ta pierwsza, orientacyjna.

    Zrobiłem kalkulator wyceny, który nie ukrywa metody: DCF i mnożnik liczone obok siebie, wszystkie parametry na wierzchu (WACC, wzrost, mnożnik EBITDA), a wynik podany jako widełki, nie jako „Twoja firma jest warta X…

  • Most nad przepaścią, z którego po drodze odpadają szare bloki; na drugi brzeg dociera mniejsza turkusowa bryła

    6 October 2026, Post in Polish

    „6× EBITDA” to nie jest cena za Twoje udziały.

    Wycena i mnożniki mówią o przedsiębiorstwie. Umowa sprzedaży – o udziałach. Pomiędzy jest most: dług netto, quasi-dług i kapitał obrotowy. W przykładzie z mojego kalkulatora most zabiera 20 % wartości firmy. I to jest…

  • Grafika do posta na LinkedIn: Budżet roczny mówi, czy firma zarobi. Nie mówi, czy w trzecim tygodniu listopada będzie na pensje.

    5 October 2026, Post in Polish

    Budżet roczny mówi, czy firma zarobi. Nie mówi, czy w trzecim tygodniu listopada będzie na pensje.

    Do tego służy prognoza gotówki na 13 tygodni: kwartał do przodu, tydzień po tygodniu, wpływy i wypływy z konkretnymi datami – nie „średnio w miesiącu". Trzynaście, bo tyle widać z realną precyzją: faktury już…

  • Grafika do posta na LinkedIn: Pracownik „na rękę" a pracownik w koszcie firmy to dwie różne liczby – i rzadko widzą je obie strony naraz.

    2 October 2026, Post in Polish

    Pracownik „na rękę" a pracownik w koszcie firmy to dwie różne liczby – i rzadko widzą je obie strony naraz.

    Do brutto dochodzą składki pracodawcy (emerytalna, rentowa, wypadkowa, FP, FGŚP), ewentualnie PPK. Kandydat porównuje netto na etacie z fakturą na B2B i te porównania zwykle są nieuczciwe wobec jednej ze stron…

All posts on my profile

Tool

Estimate what your company is worth

The same scheme I start every valuation with: a discounted forecast and a market approach, reconciled by weights, ending with a bridge from enterprise value to equity value. The result is indicative and does not replace a valuation.

Equity value

16,9m

Sensitivity to cost of capital ±1 pp: 15,9 – 18,1 m

Income approach
19,5 m
Market approach
18,0 m
Enterprise value
18,9 m
Bridge to equity value
−2,0 m

The model discounts a cash flow calculated as EBITDA after tax less maintenance capital expenditure and the increase in working capital (assumed at 4% of revenue). The result is an estimate based on seven numbers – a real valuation requires normalising the result, reviewing contracts and checking source data.

I want this calculated properly

From method to equity value

Where the figure on the right comes from. Every step can be challenged on its own, which is the point.

19,5Income approach-0,6Market adjustment18,9Enterprise value-2,0Net debt16,9Equity valuem
The market adjustment is not the gap between the two methods but forty percent of it – that is the weight the market approach carries in the blended result.

Poland in numbers

A business cheat sheet: inflation, wages, rates, FX

Twelve indicators from Statistics Poland, the NBP, Eurostat and the ECB in one place: pick a period from 2015 and every number recalculates. With a 2027 forecast and a downloadable PDF.

  • Price growth+56,6 %prices 2025 vs 2015 (CPI)
  • Minimum wage 20274 950 zł+3,0 % on the previous year
  • WIBOR 3M3,84 %monthly average, IX 2026
  • EUR rate4,3756 złmonthly average, X 2026

Questions

Before you write

Six questions that come up in the first conversation – and the answers I usually give.

How does an engagement start?

A short conversation about the problem (no commitment), then a list of the data I need and a scope proposal with a deadline. Work starts once the scope is accepted – there is no “valuation of the valuation” stage.

How long does a valuation or analysis take?

Valuation: two to four weeks from complete data. A thirteen-week cash ledger: a few days. Profitability analysis with segment accounts: two to three weeks, depending on ledger quality. Most of the time goes to questions about data, not to computing.

What data do you need?

Financial statements (ideally XML files from the registry), a trial balance, a ledger export for the period, material contracts and debt information. For profitability – also time records or cost allocation keys. If something is missing, I say so at the start.

What about confidentiality?

An NDA before the first file, data stored locally and encrypted, no client names on this site or in materials. Portfolio descriptions are anonymised: sector, problem, effect.

Who computes and who answers for it?

Tools compute – scripts, models, partly language models. I answer: for adjustments, assumptions and the conclusion. Every number in a document has a source the other side can check, and that is a rule I do not depart from.

Do you work remotely and outside Warsaw?

Yes – most of the work happens on data, not in the client’s office. Meetings in Warsaw or online; for clients across Poland and for companies with foreign capital (in English, in French at a working level).

Have a concrete problem with the numbers?

Write two sentences about what it is. I will tell you whether it is my kind of work and roughly how long it takes.

Let’s talk